Triangular Arbitrage Explained: Why Currency Exchange Loops Rarely Produce Free Money
A loop through dollars, euros, yen, pounds, or other currencies can look like a machine for creating money. The apparent gain is often a snapshot illusion created by different prices, access levels, costs, and timing.
Why the Same Currency Can Have Different Prices
It is reasonable to ask whether a person could start with dollars, exchange through several currencies, and return with more dollars. Currency prices do differ across banks, payment providers, brokers, and countries. A quoted euro-to-dollar rate is not one universal price. It is an offer made through a particular channel, for a particular size, at a particular moment, with particular settlement and compliance terms.
That difference is why the idea is worth understanding. A three-currency loop that appears to offer a profit is called triangular arbitrage. It is a real market concept, and sophisticated institutions use related strategies. But it is not a reliable retail-money shortcut. The very firms able to act quickly enough also help remove the mismatch.
Foreign exchange is enormous but not perfectly transparent. The Bank for International Settlements reported average global FX turnover of $7.5 trillion a day in April 2022, while noting that much trading occurs through bilateral methods rather than one public order book. That combination allows prices to differ across venues, but it also means a retail screen is rarely a direct window into the best executable price. BIS analysis of global FX turnover explains both the scale and the fragmented structure.
The Core Idea Behind Triangular Arbitrage
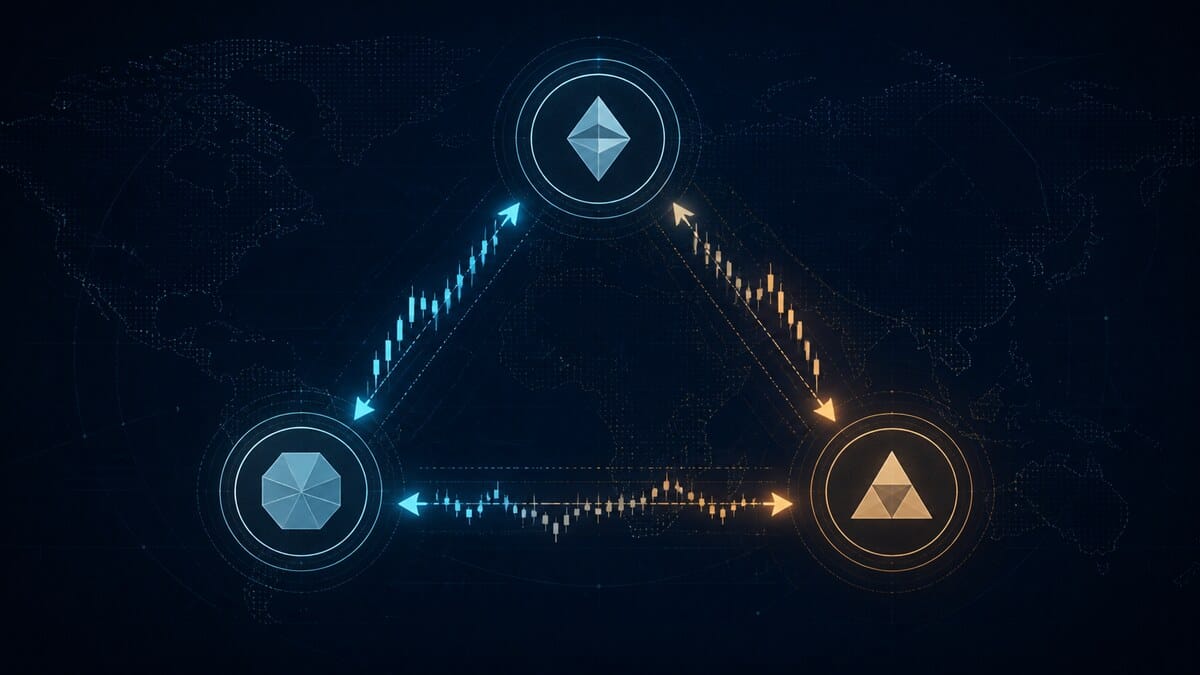
Every exchange rate can be expressed as a relationship between two currencies. If one venue quotes euros against dollars, another quotes pounds against euros, and a third quotes dollars against pounds, those three prices imply a cross-rate relationship.
Imagine a simplified loop with no fees:
- Start with USD 10,000.
- Convert dollars to euros.
- Convert euros to pounds.
- Convert pounds back to dollars.
If each price is internally consistent, the final amount should equal the starting amount. If the multiplication of the three executable rates produces more than USD 10,000, the loop contains an arbitrage opportunity in theory. If it produces less, the difference is a cost or an unfavourable set of quotes.
The word executable does the most work here. A mid-market quote is often an informational reference between the price a dealer will buy and sell. A customer who buys pays the offer; a customer who sells receives the bid. A calculation that uses three mid-prices can look profitable even when every real trade loses money after spreads.
The opportunity also has to survive long enough to trade all three legs. In a fast market, the first conversion can fill and the next two prices can move before the orders reach the market. The trader is then holding an unwanted currency position, not completing a risk-free cycle.
Why Travelling Between Banks and Countries Does Not Solve It
Physical travel makes the equation worse. Cash desks must cover handling, inventory, security, local demand, rent, and the risk of holding currency. Their published exchange rates often include a large spread. A fee-free sign does not mean cost-free conversion; the cost can be embedded in the rate.
Cross-border transfers add another layer. A bank or financial institution may charge transfer fees, use correspondent banks, apply cut-off times, request documentation, or delay a payment for screening. The International Monetary Fund's Annual Report on Exchange Arrangements and Exchange Restrictions documents that exchange arrangements, payment restrictions, and capital controls vary among member countries. A difference between two local rates may reflect a genuine constraint on moving funds rather than a profit waiting to be collected.
Even institutions need to manage settlement risk. In an FX transaction, one party can deliver the currency it sold and fail to receive the currency it bought. CLS describes payment-versus-payment settlement as a way to make one currency transfer occur only if the other does too. Its service settles payment instructions across 18 currencies, but it cannot turn every currency pair or every retail transaction into instant, costless settlement. CLS on mitigating FX settlement risk is a useful illustration of the infrastructure behind a seemingly simple exchange.
Are People Actually Doing This?
Yes, but the relevant participants are usually banks, market makers, principal trading firms, hedge funds, and specialist trading desks. Their systems can watch several venues at once, calculate cross-rates, send orders with very low latency, manage inventory, and hedge residual exposure. They also obtain institutional pricing, credit arrangements, and settlement infrastructure that an ordinary customer does not have.
The business is less like carrying cash around the world and more like running a tightly controlled technology and operations system. A small price difference can matter only when it is large enough to exceed trading costs and only when it can be captured repeatedly at substantial volume. Competition is intense precisely because the arithmetic is easy to automate.
Modern FX conduct also depends on clear execution and disclosure practices. The FX Global Code is a voluntary set of global good-practice principles for the wholesale market. It does not replace local law, but its focus on execution, transparency, governance, risk management, and settlement shows why serious currency trading is an institutional activity rather than a casual conversion game.
The Costs That Usually Erase the Gain
An apparent loop must clear every cost below before it can be called an opportunity:
- Bid-ask spreads: Each conversion usually crosses a spread. Three conversions mean three chances to pay it.
- Commissions and transfer charges: Fees may be visible, embedded in the rate, or both.
- Slippage: A quoted price may disappear before an order executes, especially at a size that consumes available liquidity.
- Latency: Data, calculation, order routing, and confirmation all take time. Faster competitors can close the gap first.
- Funding and margin: Professional firms need capital, collateral, credit lines, and controls. Borrowed exposure in retail accounts increases losses as well as gains.
- Settlement and counterparty risk: A completed trade is not the same thing as settled cash in a usable account.
- Compliance and tax administration: Identity checks, anti-money-laundering controls, reporting, local tax treatment, and currency rules can make a theoretical path unavailable or uneconomic.
Suppose a spreadsheet suggests a loop earns 0.15%. Three retail conversions with a 0.10% effective spread each would consume about 0.30% before any fixed fees or price movement. The direction of the result flips. That simple test is more useful than searching for a larger starting balance.
Is It Legal and Acceptable?
Buying and selling currencies through properly authorised providers is generally a normal commercial activity. Arbitrage itself is not automatically illegal. The legal answer changes when a person crosses borders, borrows to increase exposure, solicits money from others, operates a dealing business, evades exchange controls, misrepresents transactions, or fails to meet local reporting and tax obligations.
Do not treat a currency mismatch as permission to bypass a country's exchange rules. Rules vary by country, currency, residency, payment purpose, and transaction size. The IMF's country-level exchange-arrangements material is a starting point for understanding that variability, not a substitute for local advice.
Retail FX products also deserve scepticism. In the United States, the Commodity Futures Trading Commission warns that many retail FX transactions are over the counter, meaning the customer trades against the dealer rather than through an open exchange. Its advisory says that, in the referenced reporting period, roughly two out of three accounts at registered OTC forex dealers lost money after costs. That statistic is country-specific and does not describe every provider, but the underlying lesson travels well: verify the firm, the pricing model, fees, withdrawal terms, and regulatory status before depositing funds. CFTC guidance on retail forex risks offers a practical checklist.
How Much Money Would You Need?
There is no honest minimum that turns triangular arbitrage into a beginner-friendly income strategy. More capital does not remove a bad spread, a delayed transfer, or an unfillable quote. It can amplify a small edge only after the operator has reliable execution, measured costs, appropriate access, risk limits, and legal clearance.
For an individual, the sensible starting amount is often zero trading capital. Start with a paper calculation using live bid and offer prices from one regulated provider, then include every published fee and assume a modest adverse price move. The purpose is to learn how market plumbing works, not to prove a profit. If the calculation remains positive only when using mid-prices, ignoring transfer time, or assuming simultaneous fills, it is not a workable case.
For a firm considering a genuine FX service or trading operation, capital is only one line item. The real requirements can include regulated permissions, compliance staff, liquidity relationships, technology, monitoring, reconciliations, cyber security, legal advice, working capital, and losses that arise when a hedge or settlement fails. This is why the more realistic business opportunity is often adjacent to arbitrage: transparent pricing tools, foreign-exchange education, treasury support, payment reconciliation, or compliance technology for businesses with legitimate cross-border needs.
How to Think About the Opportunity
The reader problem is real: people see conflicting currency prices and cannot tell whether they reveal value or merely different terms. A useful product or service would reduce that confusion. For example, a business could help small importers compare their all-in payment costs, explain how bid-offer spreads work, or reconcile multi-currency invoices. The customer is paying for visibility and process, not for a promise of risk-free trading returns.
The smallest sensible test is modest. Interview five businesses or freelancers that receive or make international payments. Ask which currencies they use, how long payments take, what fees surprise them, and whether they can explain their effective conversion cost. A simple calculator or education guide can test whether the pain is clear enough to justify a service. Do not handle client funds, recommend trades, or advertise returns without understanding the local regulatory position.
This market has strong demand and strong constraints. The same network effects, capital, relationships, and systems that help institutions capture brief pricing errors form a barrier to a small entrant trying to compete directly. The opportunity is better for operators who can improve information, workflows, or lawful payment decisions than for anyone seeking a mechanical currency-money loop.
Risks, Limits, and Common Mistakes
The main mistake is to confuse a displayed quote with a tradable price. The next is to borrow for a calculation that has not cleared ordinary costs. Other warning signs include a broker promising fixed or guaranteed currency profits, pressure to fund an account using digital assets, demands for extra payments before a withdrawal, or an unregistered provider with no clear physical presence.
This article is general education, not investment, tax, or legal advice. If you trade currencies, run a cross-border business, or move substantial funds, check the rules that apply where you live and transact and consult qualified local professionals where appropriate.
Final Takeaway
Currency loops can expose how foreign-exchange markets work, and triangular arbitrage is a legitimate idea in market finance. The profit is not free money lying between countries. It is a fleeting pricing discrepancy that must exceed real execution, funding, settlement, and compliance costs.
For most individuals, the right conclusion is to learn the arithmetic and avoid treating it as an income plan. For businesses, the more durable opportunity lies in helping customers understand and manage the friction that makes the apparent loop difficult in the first place.
Sources
- Bank for International Settlements: The global foreign exchange market in a higher-volatility environment
- Global Foreign Exchange Committee: FX Global Code
- International Monetary Fund: Annual Report on Exchange Arrangements and Exchange Restrictions
- CLS: Mitigating settlement risk
- Commodity Futures Trading Commission: Eight Things You Should Know Before Trading Forex