Why Compounding Feels Unintuitive but Becomes So Powerful
Compounding is not magic, and small daily actions do not guarantee success. Their power comes from reinvested gains, protected downside, better feedback, and systems that keep you moving when motivation fades.
Why This Topic Matters
Compounding is one of the most useful ideas in money, work, learning, health, and business. It is also one of the easiest to misunderstand. People hear that small actions add up, then either dismiss the idea because progress feels invisible or turn it into a slogan that ignores reality.
Both mistakes are costly. If you underestimate compounding, you may save too little, quit a useful skill too early, or miss the quiet advantage of doing the basics consistently. If you overromanticize it, you may keep repeating a weak action and call it discipline, even when the action is not improving the outcome.
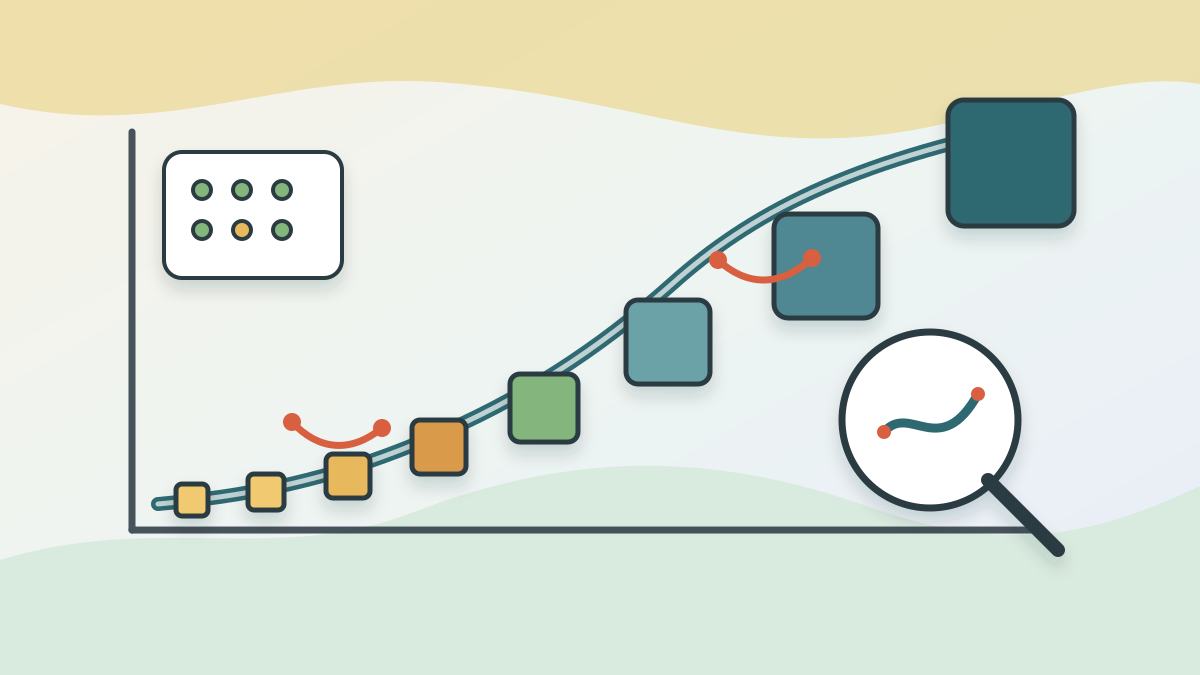
The honest version is sharper: small repeated actions can become powerful when they create a feedback loop. Money earns returns that can earn more returns. Practice creates skill that makes future practice more valuable. Trust builds reputation, and reputation makes the next opportunity easier. But compounding needs time, direction, and protection from avoidable setbacks.
That is why it feels so unintuitive. The beginning looks flat. The payoff often arrives late. The path is interrupted by boredom, doubt, bad weeks, and competing needs. The work is not only doing a little every day. It is building a system that can survive long enough for the curve to matter.
The Core Idea
Compounding means that a gain becomes part of the base that produces the next gain. In finance, the Consumer Financial Protection Bureau describes compound interest as earning interest on both the original money saved and on interest already earned. The same structure appears outside finance, though usually less cleanly: learning one concept makes the next concept easier, one trusted customer makes the next sale easier, and one healthy routine makes the next good choice less costly.
The simple arithmetic version is easy to explain. The lived version is harder. A person who improves by 1 percent once will barely notice it. A person who improves slightly and keeps the improvement can eventually create a different baseline. The effect is not because 1 percent is impressive. It is because the next step starts from the improved position.
That is the part human intuition often misses. We are good at adding: one plus one plus one. We are weaker at imagining growth that feeds on itself. Research on exponential-growth bias finds that people tend to underestimate compound growth, especially in financial decisions. In one experiment, participants showed both underestimation and overconfidence in their ability to handle exponential-growth problems, which helps explain why people may not seek tools even when tools would help.
Compounding also works in reverse. Fees, debt interest, missed maintenance, poor sleep, and repeated small compromises can accumulate. The U.S. Securities and Exchange Commission's investor education materials warn that investment fees can look small while reducing the amount left to earn returns over time. The same logic applies to attention, habits, and businesses: small drags become expensive when they persist.
Why It Feels So Unintuitive
The first reason is that compounding is quiet early. A small deposit, a short practice session, or a modest improvement may be real and still look unimpressive. Linear effort gives the brain a clearer reward: do something, see something. Compounding often asks for action before the visible reward arrives.
The second reason is present bias. People tend to give extra weight to immediate comfort, cash, convenience, and relief. An NBER field experiment with low-income tax filers found behavior consistent with present-biased preferences: people were more willing to take earlier payment when deciding on the spot than when deciding in advance. That matters because compounding usually pays later while the cost is paid now.
The third reason is noise. In investing, markets move up and down. In learning, some days feel worse than the day before. In business, a good process can produce a bad week. When feedback is noisy, people confuse temporary results with permanent truth. They stop too early because the curve has not announced itself.
The fourth reason is identity. Repetition can feel humiliating when the result is still small. Saving a modest amount, writing one page, walking for ten minutes, or practicing one skill can feel beneath the size of the goal. The mind compares the action with the dream and concludes that the action is too small to matter.
The fifth reason is that slogans hide constraints. "Do a little every day" sounds simple, but real life contains illness, care work, job stress, unstable income, mental fatigue, and unexpected obligations. Resilience is not a personality trait that floats above those constraints. It is partly a design problem: how can the useful action be made small, repeatable, recoverable, and tied to feedback?
When Small Daily Actions Really Work
Small daily actions work best when the action changes the starting point for tomorrow. Saving can work this way because the saved amount can remain in the account and earn returns. Learning can work this way because memory, pattern recognition, and confidence can accumulate. Business development can work this way when useful content, customer relationships, process improvements, or distribution assets remain after the work is done.
They also work when the action is specific. "Get better with money" is vague. "Automate a small transfer after every payment" is operational. "Learn investing" is vague. "Read one annual report section and write three notes" is operational. A specific action can be repeated and improved.
The strongest daily actions usually have four traits:
- They are small enough to survive bad days.
- They are meaningful enough to affect the base over time.
- They produce or protect an asset: cash, skill, health, trust, knowledge, or distribution.
- They include feedback, so repetition can become improvement rather than ritual.
This is where habit research helps. In a real-world habit-formation study, Phillippa Lally and colleagues found that automaticity developed gradually and varied widely by person and behavior, with one missed opportunity not materially disrupting the process. That is useful because it argues against fragile streak thinking. Missing once is not the same as failing. The issue is whether the system resumes.
Implementation intentions can also help. A meta-analysis by Peter Gollwitzer and Paschal Sheeran found that if-then plans had a medium-to-large effect on goal attainment. The practical lesson is plain: do not rely only on wanting the outcome. Decide the cue and the response before the difficult moment arrives.
When the Idea Is Oversold
The compounding story becomes misleading when it ignores quality. Ten minutes of distracted practice is not the same as ten minutes of focused practice. Repeating the same mistake can compound the mistake. In expertise research, deliberate practice is not just time spent. It involves focused work on weaknesses, feedback, and adjustment. Other researchers have also argued that practice alone does not explain all expert performance. So the objective view is not "practice guarantees greatness." It is "structured practice gives improvement a better chance."
The idea is also oversold when the action is too small relative to the goal. A tiny saving habit is better than no habit, but it may not be enough for retirement, a house deposit, or business capital. A daily page may build a writing habit, but a book still needs structure, revision, and publishing decisions. Small actions are starters and multipliers, not substitutes for arithmetic.
Compounding can also be broken by large losses. In money, high-interest debt, major fees, panic selling, or concentrated risk can overwhelm careful saving. In health, injury can erase progress if the routine ignores recovery. In business, a reputation mistake can undo years of trust. The downside matters because compounding needs continuity.
Finally, compounding is not equally available to everyone. A person with stable income, time, health, and social support can compound more easily than someone under constant stress. That does not make the idea false. It means advice should be humane. The first step may be reducing volatility, not optimizing growth.
How to Make Compounding Easier to Stick With
The first move is to make the curve visible. Use a calculator for savings, debt, fees, or time. The CFPB and Investor.gov both point readers toward compound-interest tools for understanding how rate, time, and frequency change outcomes. Outside finance, use a simple tracker for leading indicators: practice sessions completed, pages drafted, customer calls made, workouts done, invoices sent, or hours slept.
The second move is to automate the good action where possible. Automated transfers, scheduled study blocks, recurring reviews, default calendar slots, and prepared environments reduce the need to win the same argument every day. Automation does not remove choice. It moves the choice to a calmer moment.
The third move is to use if-then planning. If the salary arrives, then a set amount moves to savings. If it is after breakfast, then the language lesson starts. If a client meeting ends, then notes go into the CRM. If travel breaks the normal routine, then the minimum version happens instead. This turns resilience from a mood into a rule.
The fourth move is to protect the floor. A minimum version keeps the chain alive without pretending every day is equal. Five minutes of practice is not the same as an hour, but it keeps the cue-response link alive. A small transfer is not a full savings plan, but it preserves the habit while income is tight. The minimum should be small enough to do under stress and honest enough to count.
The fifth move is to review the system, not just the streak. Once a week or once a month, ask: is this action still connected to the result? What feedback did I get? What should be adjusted? What risk could break the compounding path? This prevents blind repetition.
The sixth move is to separate resilience from self-punishment. Resilience is not forcing the same output every day forever. It is returning to the system after interruption, adjusting the load, and protecting the long-term base. Rest, recovery, and reallocation can be part of compounding when they keep the system alive.
Practical Takeaways
For personal finance, the useful action is often boring: save automatically, avoid high-interest debt where possible, keep fees visible, and give money time. Readers should check local tax rules, account protections, retirement systems, and qualified local advisers where needed. The compounding principle travels globally, but the products and rules do not.
For learning, the useful action is not merely time spent. Pick a narrow skill, practice slightly beyond comfort, get feedback, and revisit hard parts. A small amount of deliberate practice is usually better than a larger amount of unfocused repetition.
For business, look for assets that do not disappear after the day ends: a better onboarding process, a useful article, a customer insight, a supplier relationship, a reusable template, a trusted brand promise, or a cleaner metric. Busywork does not compound simply because it is repeated.
For resilience, design for interruption. The question is not "How do I never miss?" It is "What happens after I miss?" A resilient system has a restart rule, a minimum version, and a review rhythm.
For judgment, remember the caveat: compounding is powerful but not mystical. It magnifies what is repeated. If the repeated action is useful, protected, and improved, time can help. If the repeated action is weak, misdirected, or fragile, time may only reveal the weakness.
How to Think About the Opportunity
There is also a business opportunity around compounding itself. People need help seeing delayed effects before those effects become obvious. That can support calculators, coaching, financial education, habit apps, workplace learning programs, investing explainers, debt-repayment tools, and accountability systems.
But the best products in this area should avoid motivational fog. A useful compounding tool does three things: it makes the future visible, it turns intention into a specific next action, and it helps the user recover after interruption. The customer problem is not lack of inspiration. It is the gap between a long-term benefit and a short-term cost.
A small first test could be simple: choose one audience, one compounding problem, and one measurable behavior. For example, new investors may need a fee-impact calculator. Freelancers may need a weekly business-development tracker. Language learners may need a missed-day recovery plan. Test whether people use the tool twice, not whether they admire the idea once.
Risks, Limits, or Common Mistakes
The most common mistake is confusing compounding with guaranteed outcomes. Returns vary. Careers change. Habits break. Health, family, and economic shocks can interrupt plans. Good advice should increase the odds, not promise certainty.
Another mistake is ignoring negative compounding. Debt interest, fees, poor sleep, reputational damage, and low-quality repetition can also accumulate. Sometimes the highest-return move is not adding a new habit. It is stopping a leak.
A third mistake is worshiping consistency at the expense of direction. Consistency is valuable only when the action points somewhere useful. If the routine is not producing learning, cash flow, trust, strength, or clarity, it may need redesign.
A fourth mistake is treating resilience as willpower alone. Environment, reminders, defaults, social support, energy, and recovery matter. The more important the goal, the less it should depend on daily emotional heroics.
Final Takeaway
Compounding feels unintuitive because the early signs are small, the payoff is delayed, and the human mind is better at straight lines than curves. That does not make it weak. It makes it easy to abandon before it starts working.
The practical answer is not blind faith in small actions. It is better design: choose actions that improve the base, automate what can be automated, use if-then plans, protect against big losses, build feedback, and allow recovery after missed days. Little by little works best when each little step makes the next step easier, smarter, or safer.
Sources
- Consumer Financial Protection Bureau: How compound interest works
- Investor.gov: Compounding interest glossary
- Investor.gov: How fees and expenses affect your investment portfolio
- Journal of Economic Psychology: Exponential-growth bias and overconfidence
- NBER: Time-Inconsistency and Saving
- European Journal of Social Psychology: How habits are formed
- Advances in Experimental Social Psychology: Implementation intentions and goal achievement
- Frontiers in Psychology: Deliberate practice and limits on practice effects